Introduction
Many people believe that getting a home loan with a low CIBIL score is impossible. While a higher credit score certainly improves your chances, a low CIBIL score does not automatically mean your application will be rejected. Many banks and NBFCs consider several factors beyond your credit score, such as your income, employment stability, repayment capacity, and property value.
In this guide, we’ll explain how you can improve your chances of getting a home loan even with a low CIBIL score.
What is a CIBIL Score?
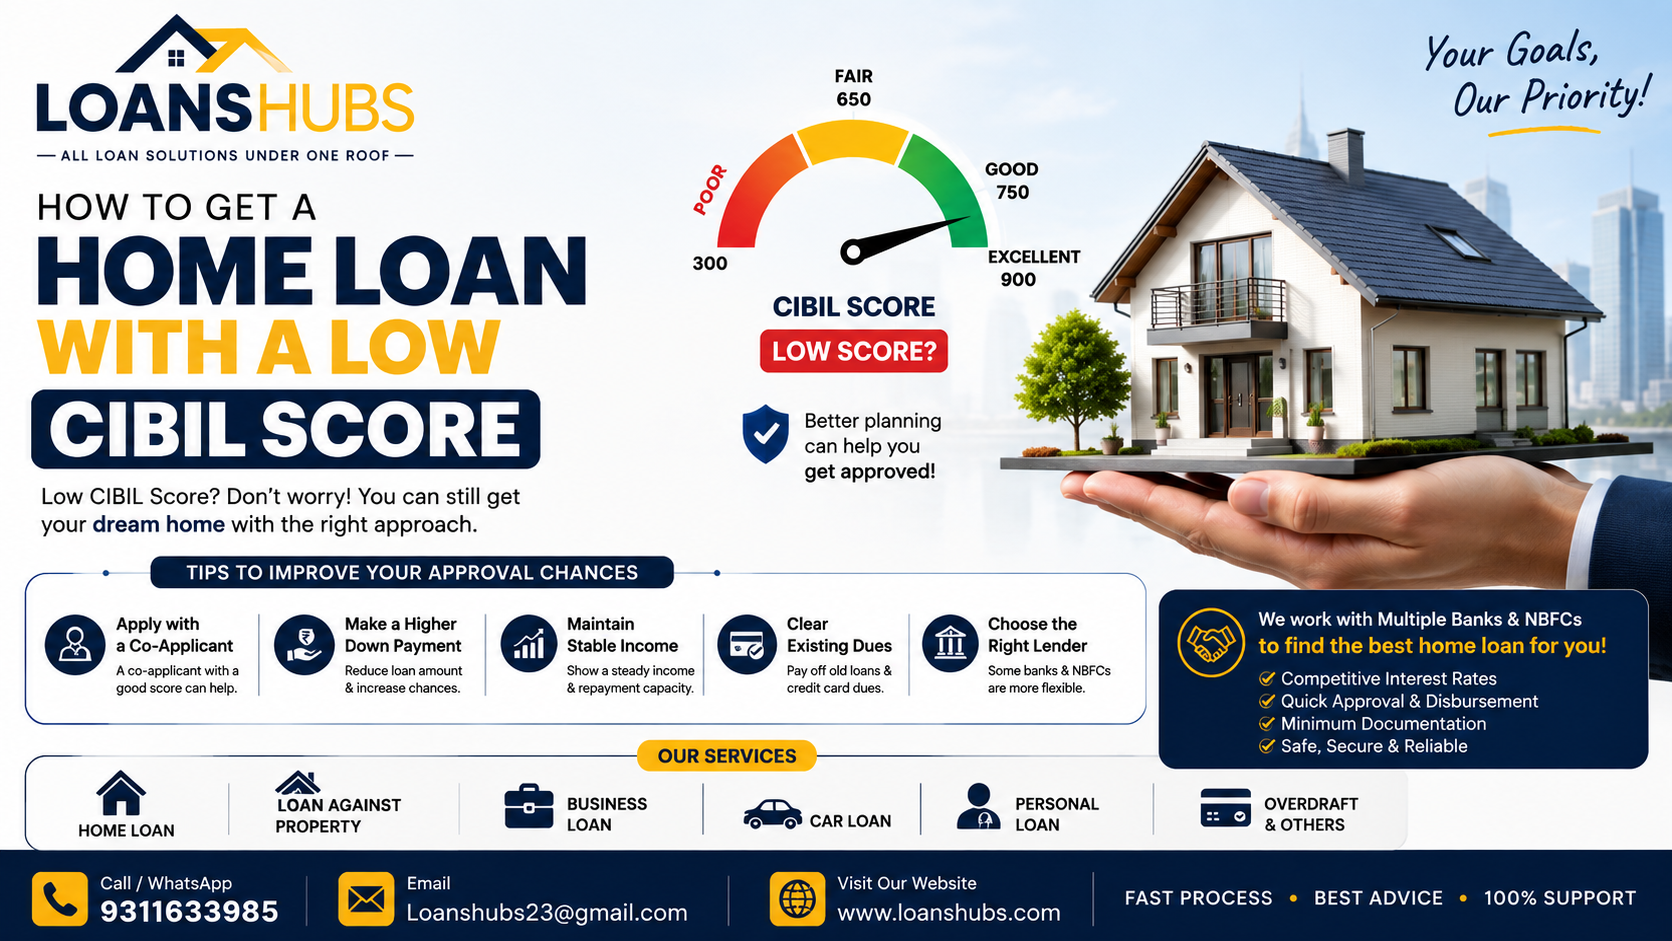
A CIBIL Score is a three-digit number ranging from 300 to 900 that reflects your creditworthiness based on your credit history.
Generally:
- 750–900: Excellent
- 700–749: Good
- 650–699: Fair
- Below 650: Low
A score of 750 or above is usually preferred by most lenders, but borrowers with lower scores may still qualify under certain conditions.
Why Does Your CIBIL Score Matter?
Banks use your CIBIL score to evaluate the risk of lending money.
A higher score often results in:
- Faster loan approval
- Better interest rates
- Higher loan eligibility
- Easier documentation process
A lower score may lead to:
- Higher interest rates
- Lower loan amount
- Additional verification
- Requirement of a co-applicant or guarantor
Can You Get a Home Loan with a Low CIBIL Score?
Yes.
Many banks and NBFCs provide home loans to applicants with low CIBIL scores if they meet other eligibility criteria. Your overall financial profile plays an important role in the lender’s decision.
Tips to Get a Home Loan with a Low CIBIL Score
1. Improve Your Credit Score Before Applying
If possible, delay your application for a few months and work on improving your score.
You can:
- Pay EMIs on time
- Clear overdue credit card bills
- Avoid loan defaults
- Reduce credit card utilization
- Check your credit report for errors
Even a small improvement in your score can make a significant difference.
2. Apply with a Co-Applicant
Adding a spouse, parent, or earning family member with a good CIBIL score can increase your chances of loan approval.
It may also help you receive:
- Better interest rates
- Higher loan eligibility
- Faster approval
3. Choose the Right Lender
Different banks and NBFCs have different credit policies.
Some lenders are more flexible and evaluate:
- Monthly income
- Job stability
- Existing liabilities
- Property value
Comparing lenders before applying can improve your approval chances.
4. Maintain a Stable Income
A stable income reassures lenders that you can repay the loan.
Keep ready:
- Salary slips
- Bank statements
- Income Tax Returns (ITR)
- Employment proof
Self-employed applicants should maintain proper business and income records.
5. Pay Off Existing Loans
Before applying:
- Close small personal loans
- Pay outstanding EMIs
- Clear credit card dues
Reducing your debt improves your debt-to-income ratio and strengthens your application.
6. Make a Higher Down Payment
Paying a larger down payment reduces the loan amount required and lowers the lender’s risk.
For example:
If you’re buying a ₹50 lakh property, paying 25–30% as a down payment instead of the minimum amount may improve approval chances.
7. Avoid Multiple Loan Applications
Submitting applications to many banks within a short period results in multiple credit inquiries, which can negatively affect your credit score.
Instead:
- Compare lenders first
- Check eligibility
- Apply only where you have a good chance of approval
8. Keep All Documents Ready
Typical documents include:
- PAN Card
- Aadhaar Card
- Address Proof
- Income Proof
- Salary Slips
- Bank Statements
- Property Documents
- Passport-size Photographs
Complete documentation speeds up the approval process.
Common Mistakes to Avoid
- Missing EMI payments
- Ignoring credit report errors
- Applying to multiple lenders simultaneously
- Maxing out credit cards
- Taking unnecessary personal loans before applying
How LoansHubs Can Help
At LoansHubs, we work with multiple banks and NBFCs to help customers find the most suitable home loan options based on their financial profile.
Our services include:
- Home Loan Assistance
- Loan Against Property
- Balance Transfer
- Business Loan
- Personal Loan
- Expert Loan Consultation
- Assistance with Documentation
- Support for Applicants with Low CIBIL Scores
Our team compares multiple lenders to help you choose the best available option.
Leave a Reply